

In three years, a Bengaluru startup crossed ₹1,000 crore in cumulative revenue selling specialty chemicals — without owning a single factory. Scimplify, founded in 2023, runs an asset-light B2B platform: the science and R&D are in-house, while manufacturing flows through a network of more than 500 partner plants, roughly 90% of them in India. It is a manufacturing company that manufactures nothing itself — and investors have poured in about $53 million betting the model scales.
The founders who saw the supply gap
Scimplify was founded in 2023 by Sachin Santhosh, Salil Srivastava and Dheeraj Dhingra, with backgrounds spanning IIT Madras and IIM Bangalore. Srivastava previously led the chemicals vertical at Zetwerk, the manufacturing-services unicorn; Santhosh had stints at OfBusiness and Bizongo. They had watched the same problem from different angles: global buyers wanted specialty chemicals from India, but discovering reliable manufacturers, qualifying them and managing quality across hundreds of small plants was punishing work. Scimplify’s answer was to become the layer in between — a full-stack platform the company calls ATOMS, which lists chemicals from more than 5,000 factories and 200-plus manufacturers across 10 countries, according to TechCrunch.
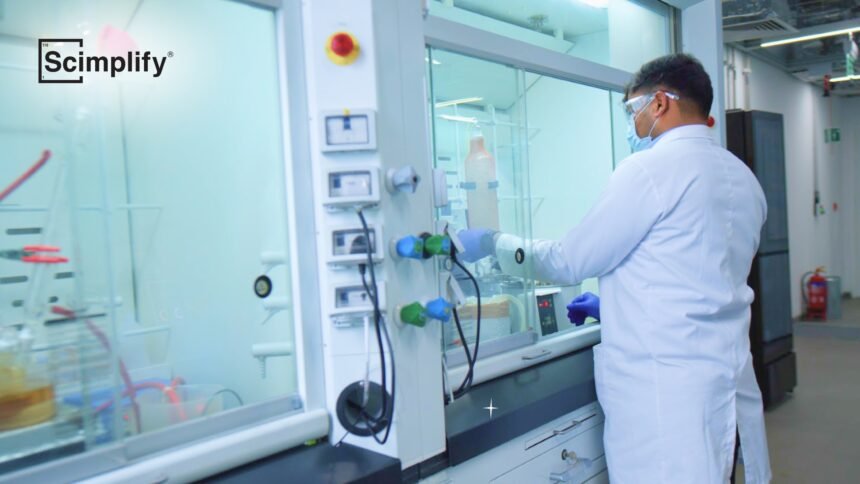
The distinction matters. Scimplify is not a marketplace that merely matches buyers and sellers. The company does its own chemistry — synthesis development, process optimisation, quality systems — then hands qualified recipes to partner plants with idle capacity. The customer gets a single accountable supplier; the plant gets utilisation. In an industry where trust is the scarcest input, owning the science while renting the steel is the whole thesis.
₹1,000 crore — read the number carefully
The headline figure needs precise handling, because it is easy to misread. The Hindu BusinessLine reported in July 2026 that Scimplify had crossed “₹1,000 crore in cumulative revenue since 2023” — cumulative, not annual. For context, the Economic Times put FY25 revenue at “over ₹200 crore,” with the company targeting a doubling this year. That is still remarkable for a three-year-old company in a heavy industry, but it is a different statement from a ₹1,000-crore run rate.
The profitability picture needs the same care. BusinessLine described the company as “operationally, excluding R&D investments, profitable over the past four months,” while Entrepreneur India called it “approaching profitability.” The honest phrasing is “nearing profitability” — not “profitable.” Similarly, the geographic footprint: company and creator materials cite 40 countries, while BusinessLine reported 35. This post uses “35+ countries” — with offices or teams in the US, Japan, the UAE and Indonesia, a sourcing operation in China, and expansion underway into Europe and Latin America.
₹1,000 crore in cumulative revenue in three years — selling chemicals without owning a single factory.
The new growth engines
The most interesting part of the Scimplify story is where it is heading. According to BusinessLine, new verticals — semiconductor etchants, specialty coolants, dielectric oils, battery chemicals, defence chemicals, critical minerals and rare earths, and chemicals for AI infrastructure — have grown from under 10% of revenue to 40% in about six months. These are precisely the chemistries where India wants domestic supply chains: chipmaking inputs, energy-transition materials, defence-grade compounds. If the platform thesis works anywhere, it should work here, where buyers will pay for qualified, traceable Indian supply — the same domestic-manufacturing logic PopVax is applying to RNA vaccines.
The R&D backing this push is real money: a ₹15-crore Center for Innovation laboratory in Bengaluru, ₹25–30 crore in annual R&D spend across Bengaluru, Hyderabad and Gujarat, more than 15 scientists, and AI deployed for synthesis prediction and process optimisation, per company disclosures. That is the moat — anyone can aggregate plants, but few can develop the chemistry that makes the aggregation trustworthy.
Key takeaway
The takeaway: Scimplify’s bet is that in specialty chemicals, the scarce asset isn’t the factory — it’s the science, the quality system and the buyer relationship. ₹1,000 crore cumulative in three years suggests buyers agree; the next test is whether the semiconductor and defence verticals can carry the doubling the company targets. Life-sciences manufacturing is having a moment — Avay’s bioprinters are part of the same wave.
What to watch
Three milestones will decide whether this is a durable company or a fast trade: does the reported $30–40 million Hitachi Ventures-led round close at the ~$300 million valuation the Economic Times cited; does the company cross into clean, sustained profitability rather than “operationally excluding R&D”; and can the new high-spec verticals keep compounding while the core pharma, agrochemical and personal-care business holds. The asset-light model means capital efficiency — but it also means Scimplify’s quality is only as good as its weakest partner plant, which is why the in-house science matters more than the network size.
What is Scimplify?
A Bengaluru B2B specialty-chemicals platform founded in 2023 by Sachin Santhosh, Salil Srivastava and Dheeraj Dhingra. It develops chemistry in-house and manufactures through 500+ partner plants (~90% in India), serving 100+ global customers across pharma APIs, agrochemicals, personal care, flavours and fragrances — plus newer semiconductor, battery and defence verticals.
Did Scimplify really do ₹1,000 crore in revenue?
The Hindu BusinessLine reported ₹1,000 crore in cumulative revenue since 2023 — cumulative, not annual. FY25 revenue was over ₹200 crore per the Economic Times, with the company targeting a doubling. It is a three-year total, still remarkable for the timeframe.
Is Scimplify profitable?
Not quite. BusinessLine described it as operationally profitable excluding R&D for about four months; Entrepreneur India said “approaching profitability.” The accurate phrasing is “nearing profitability.”
How does the asset-light model work?
Scimplify owns the science — synthesis development, process design, quality systems — and rents manufacturing capacity from partner plants. Its ATOMS platform lists chemicals from 5,000+ factories and 200+ manufacturers across 10 countries, per TechCrunch. Customers get one accountable supplier; plants get utilisation.
Who has funded Scimplify?
About $53 million total: a $3.6M seed, $9.5M Series A (Aug 2024, Omnivore + Bertelsmann) and a $40M Series B (Mar 2025, co-led Accel + Bertelsmann at a $150M post-money valuation). The Economic Times reported talks for a $30–40M round led by Hitachi Ventures at around a $300M valuation.
More Read
Sources & further reading
- The Hindu BusinessLine: Scimplify bets on AI, semiconductors and defence chemicals — July 2026 report on cumulative ₹1,000 cr revenue, new growth verticals and profitability status
- Economic Times: Scimplify in talks to raise $30–40M from Hitachi Ventures — Funding talks, valuation and FY25 revenue figures
- TechCrunch: Scimplify raises $40M Series B — Series B details and the ATOMS platform’s scale